Follow the Conduit: How a Single Interstate Fiber Corridor Gets Built, Owned, and Monetized
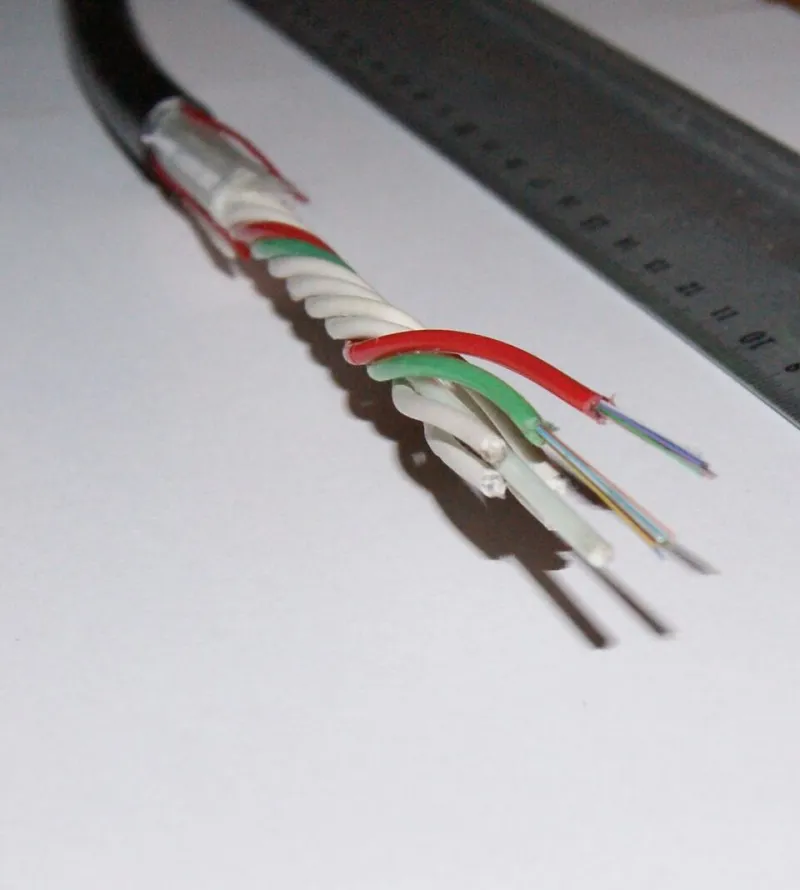
Photo: Asurnipal, CC BY-SA 4.0, via Wikimedia Commons
Somewhere beneath a two-lane highway in the Missouri Ozarks, a conduit holds strands of glass that could carry more traffic than every household in three counties will ever consume. Those strands are dark. Nearby, a rural electric co-op is waiting on a federal grant decision before it can afford to light even a fraction of them.
This is the paradox at the heart of American broadband: the physical backbone often exists where the service does not. Understanding why requires following a single hypothetical corridor — call it the I-70 relay between Kansas City and St. Louis — from the first right-of-way filing to the moment a lit building comes online.
Phase One: The Right-of-Way Paperwork Nobody Sees
Long before a backhoe rolls, the fate of a fiber corridor is decided in filings with state departments of transportation, county commissions, and sometimes the federal government when the route crosses Bureau of Land Management or Forest Service land. A long-haul builder must secure permits for every mile of state highway shoulder, negotiate railroad crossings with Class I freight carriers, and satisfy environmental review requirements that can stretch months into years.
The cost structure is unforgiving. Make-ready work — moving utility poles, reinforcing bridges, boring under waterways — routinely runs $50,000 to $150,000 per mile in contested terrain. A 250-mile corridor can carry nine figures in construction cost before a single customer is billed.
This is why the map of American long-haul fiber looks the way it does. Routes follow highways and rail lines because those rights-of-way were engineered a century ago to be straight, graded, and legally accessible. Where the interstate goes, the glass tends to follow. Where the interstate skips — as it does across broad swaths of the Dakotas, Appalachia, and the rural South — the backbone skips too.
Phase Two: Who Actually Owns the Route
Once built, the corridor typically has three or four owners whose interests rarely align.
A national wholesale carrier may hold the original conduit and lease capacity to everyone else. A regional provider may own a parallel older route built during the dot-com era. A hyperscaler building data center interconnects may have bought or constructed yet another path, driven by latency budgets measured in microseconds rather than subscriber counts.
Critically, much of the capacity is sold not as lit service but as dark fiber — raw, unilluminated strands leased for twenty years at a time. Dark fiber pricing is opaque, negotiated deal by deal, and historically favored buyers who could afford the capital expense of their own optical electronics. That excluded almost everyone except the largest carriers and technology companies.
The rural gap is not primarily a glass problem. It is a last-mile economics problem: the backbone passes through, but the cost of extending lateral connections to sparsely populated towns never penciled out. Record federal spending through the Broadband Equity, Access, and Deployment program is designed to fix exactly this, subsidizing the lateral build. But grant timelines, workforce shortages, and supply-chain delays mean the money and the strands are not meeting as quickly as policymakers hoped.
Phase Three: Where SDN Changes the Equation
Here is where the story diverges from the way it played out twenty years ago.
A regional ISP or mid-size enterprise that leases a pair of dark strands along our hypothetical corridor no longer needs a six-figure optical engineering staff to make them productive. Software-defined optical line systems allow the lessee to provision wavelengths remotely, turning up 100-gigabit channels through a vendor's controller rather than a truck roll and a rack of proprietary gear.
Consider a hypothetical community college system with campuses in Columbia and St. Louis. Under the old model, it would buy managed circuits from a carrier and pay recurring charges for bandwidth upgrades. Under the new model, it leases two dark strands, installs coherent pluggable optics, and runs the entire optical layer under an SDN controller that treats wavelength provisioning like any other policy object. The upgrade from 100G to 400G becomes a software and optics decision, not a contract negotiation.
For regional ISPs, the same logic applies to their transport backhaul. Instead of purchasing lit 10G circuits whose pricing reflects the carrier's margin, they can aggregate demand across member towns, lease dark fiber collectively, and manage the network through automation tooling that a three-person engineering team can realistically operate.
What Enterprises Should Watch
Three developments are worth monitoring if your organization depends on interstate transport:
First, dark fiber availability is expanding as hyperscalers overbuild and divest routes they no longer need. Secondary markets for conduit and strands are becoming more liquid.
Second, open optical line systems are commoditizing the transport layer. When the line system is disaggregated and controller-driven, the moat around incumbent lit-service pricing shrinks.
Third, federal subsidy timelines will create windows. When BEAD-funded last-mile projects reach construction in a given county, the demand for nearby backhaul capacity spikes. Corridor owners who leased capacity early at fixed rates will capture that upside; those who waited will pay market rates.
The Bottom Line
The quiet fight over America's fiber routes is not a fight about whether the glass exists. It is a fight about who can afford to light it, who controls the rights-of-way, and whether the software layer has matured enough to let smaller players participate. On corridors like our hypothetical I-70 relay, the answer is increasingly yes — provided regional ISPs and enterprises understand that the backbone is no longer something you simply buy. It is something you can now, finally, operate yourself.